
Seasonal Cash Flow for Card Shops: How to Handle Slow Months Without Selling Inventory
Summary
Seasonal cash flow swings are normal for card shops—but they don’t have to hurt your business. By planning ahead, managing inventory smartly, controlling expenses, and using flexible funding strategies, you can handle slow months without selling valuable stock or missing growth opportunities.
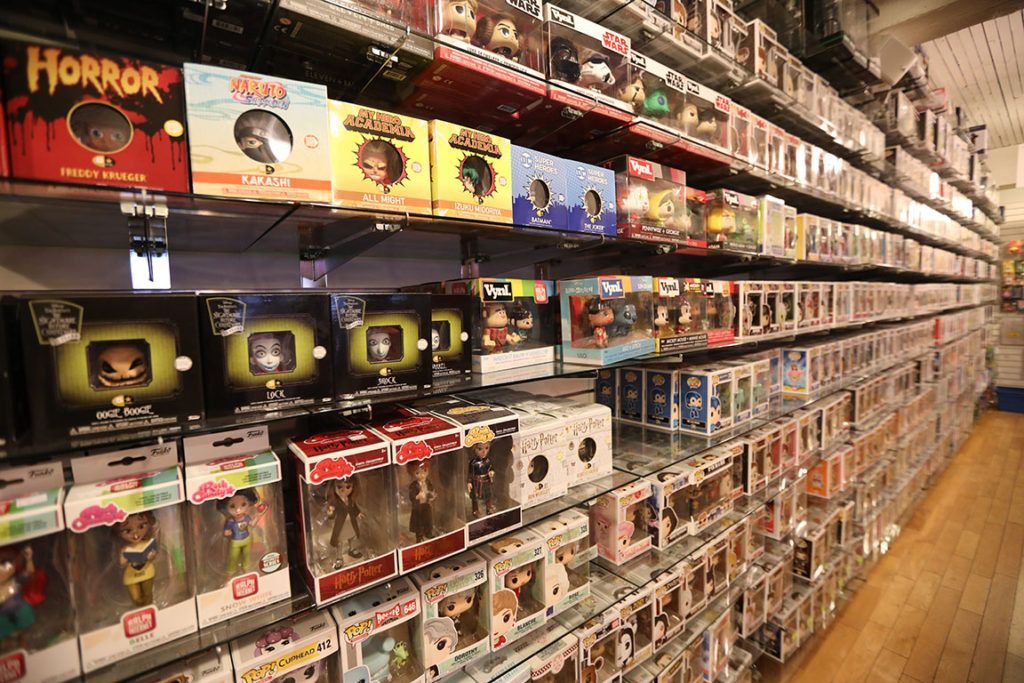
Smart strategies to keep your business stable year-round—even when sales slow down
Every card shop owner knows this feeling.
One month, your shop is buzzing. Sales are strong. Inventory is flying off the shelves.
Then suddenly…
Things slow down.
Foot traffic drops. Online orders shrink. New releases dry up. And cash flow gets tight.
This cycle is completely normal in the trading card industry—but many shop owners panic and make the same mistake:
They start selling valuable inventory just to cover short-term expenses.
That decision can hurt long-term profits and limit future growth.
The good news?
There are smarter ways to handle seasonal cash flow challenges—without sacrificing your best inventory.
Let’s break down exactly how.
What Is Seasonal Cash Flow for Card Shops? (Quick Answer)
Seasonal cash flow refers to predictable periods when a card shop’s revenue drops due to slower customer demand, fewer product releases, or off-peak buying seasons.
Managing seasonal cash flow means planning ahead so your shop can operate smoothly during slower months without liquidating inventory.
Why Card Shops Experience Seasonal Slowdowns
Unlike many retail businesses, card shops operate on unique demand cycles.
These slow periods usually happen because of:
1. Release Calendar Gaps
When major sets aren’t launching, customer excitement naturally dips.
Fewer new products means fewer impulse purchases.
2. Post-Holiday Spending Drops
After busy holiday seasons, customers often cut back on spending.
This leads to slower sales early in the year.
3. Market Trend Cycles
Interest in certain games or sports can shift, affecting buying patterns.
Collectors often wait for market movements before purchasing.
4. Summer Slumps
Many shops see reduced traffic during vacation months.
Customers simply spend less time shopping.
The Biggest Mistake During Slow Months
When revenue dips, many shop owners respond by selling premium inventory quickly.
This might solve short-term cash needs—but it creates long-term problems.
Selling valuable inventory early can:
- Reduce future profit potential
- Limit ability to attract collectors
- Lower overall inventory quality
- Slow future growth
The goal isn’t to sell faster—it’s to manage cash smarter.
Strategy #1: Build a Seasonal Cash Flow Cushion
The best way to survive slow months is to prepare during busy ones.
Smart shops set aside a portion of peak-season profits as a reserve.
This cushion helps cover:
- Rent
- Payroll
- Utilities
- Basic operating expenses
Even saving a small percentage during strong months can prevent panic decisions later.
Strategy #2: Track Your Seasonal Patterns
Many shop owners underestimate how predictable their sales cycles actually are.
Look at your past year and identify:
- Highest revenue months
- Lowest sales periods
- Release-driven spikes
- Holiday trends
Once you know your patterns, you can plan inventory purchases and expenses accordingly.
Predictability is your biggest advantage.
Strategy #3: Adjust Inventory Buying During Slow Periods
One common mistake is continuing aggressive inventory purchases even when sales are slowing.
Instead, shift your strategy.
During slower months:
- Focus on fast-moving products
- Avoid large bulk purchases
- Reduce speculative buys
- Prioritize high-demand items
This protects your cash flow while keeping your shelves active.
Strategy #4: Increase Cash Flow Without Selling Inventory
Many shop owners don’t realize they have options beyond selling stock.
You can generate cash flow by:
Offering Preorders
Selling upcoming releases in advance brings in immediate cash.
Hosting Events
Tournaments and community events can drive steady income.
Expanding Online Sales
Online marketplaces help maintain consistent revenue even during local slowdowns.
Adding Value Services
Grading assistance, trade evaluations, and memberships can generate extra income streams.
Strategy #5: Control Expenses During Slow Months
When revenue dips, expense control becomes critical.
Focus on:
- Reducing unnecessary subscriptions
- Adjusting staffing schedules
- Limiting promotional spending
- Negotiating vendor terms
Small savings can make a huge difference over several months.
Strategy #6: Use Flexible Funding Strategically
One of the smartest ways to handle seasonal cash flow is using funding designed for temporary slowdowns.
This allows you to:
- Cover operating costs
- Maintain full inventory levels
- Continue growth investments
- Avoid panic selling
Strategic funding acts as a safety net—not a long-term burden.
How Strong Cash Flow Planning Improves Growth
When you manage seasonal cash flow effectively, your business becomes more stable.
This leads to:
- Better purchasing power
- Stronger inventory quality
- Improved customer confidence
- Faster long-term growth
Consistency beats short-term survival tactics every time.
Signs Your Card Shop Needs a Seasonal Cash Flow Plan
You likely need a better strategy if:
- You sell premium inventory during slow months
- Revenue swings create stress
- You delay inventory purchases due to cash shortages
- Expenses feel unpredictable
Planning ahead eliminates these problems.
FAQ: Seasonal Cash Flow for Card Shops
What causes seasonal cash flow problems in card shops?
Sales cycles, release schedules, market trends, and customer spending habits all contribute to predictable slow periods.
Should I sell inventory during slow months?
It’s better to preserve valuable inventory and use cash flow management strategies instead.
How can I prepare for slow seasons?
Track revenue patterns, build cash reserves, control expenses, and adjust inventory purchasing.
Can funding help manage seasonal cash flow?
Yes. Flexible funding can stabilize operations during slow periods without forcing inventory liquidation.
What’s Next: Turning Slow Months Into Stable Growth
Seasonal slowdowns don’t have to feel stressful.
With the right planning, you can turn these quieter periods into opportunities to strengthen your business, optimize operations, and prepare for the next growth cycle.
Our lead service helps connect card shop owners with funding solutions specifically designed for seasonal cash flow challenges.
The next step is simple: speak with a representative to explore your options, understand what you qualify for, and discover how the right strategy can help you maintain inventory, stabilize revenue, and grow confidently year-round.










